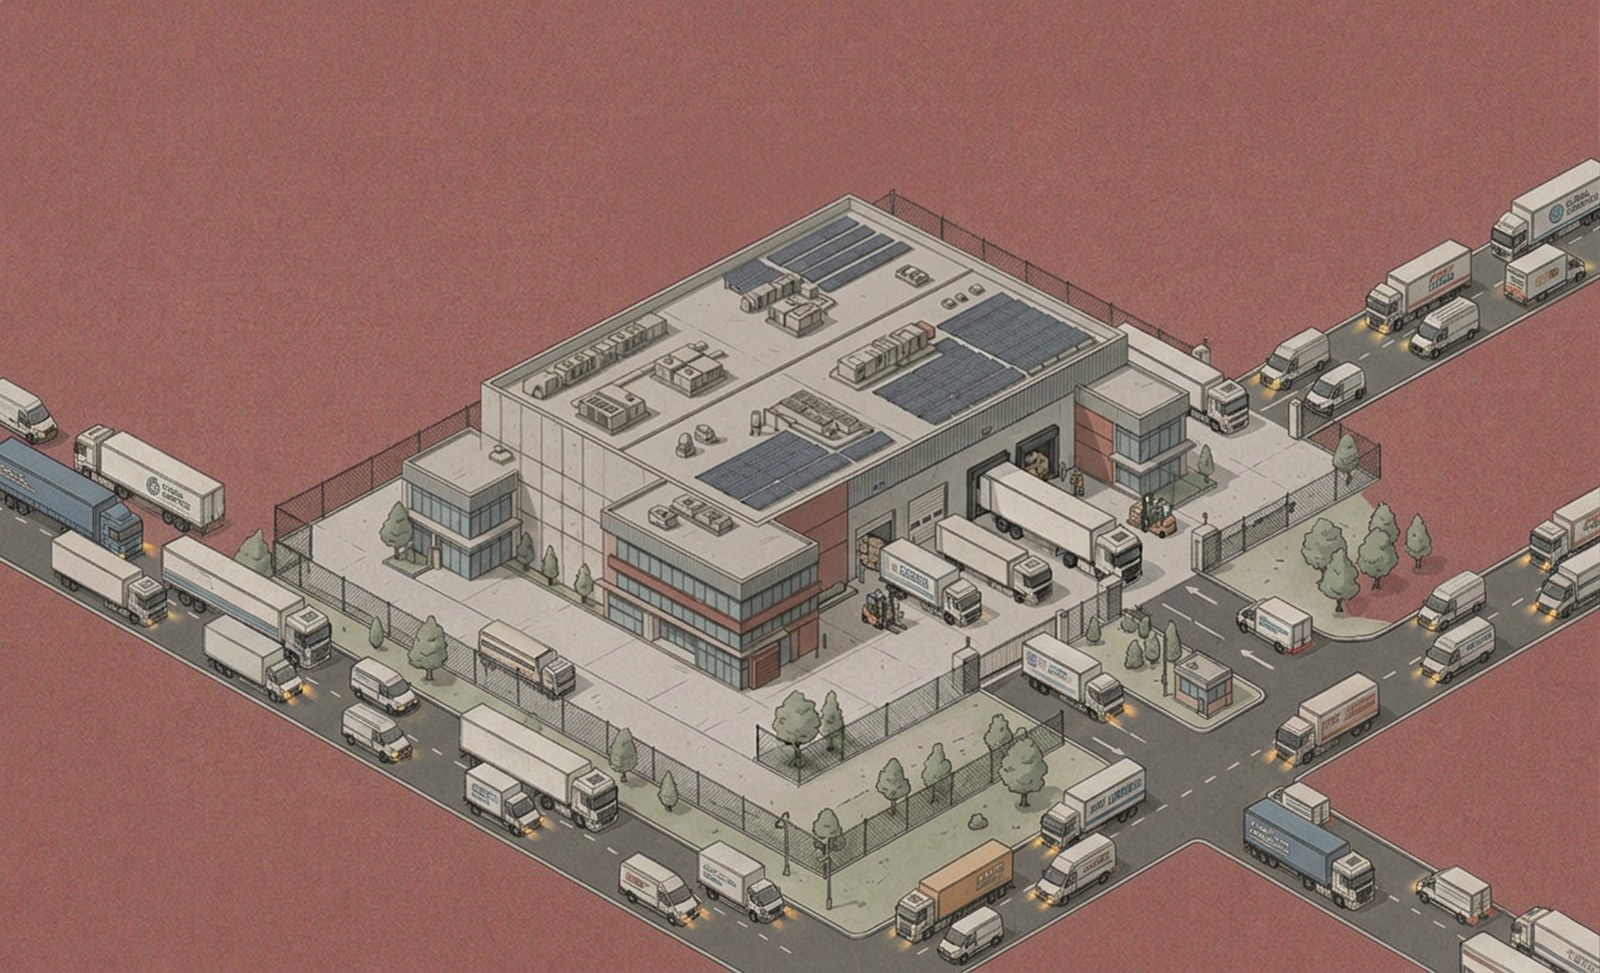
E-commerce is the demand; logistics real estate is the asset
Consumption is compounding at double digits while the infrastructure that fulfills it lags. That gap is where the durable returns sit.
Sources: AMVO; AMVO 2025. Figures are the most recent available at time of writing and are provided for context, not as investment advice.
E-commerce in Mexico is compounding at a rate most sectors would envy. Online sales reached 789.7 billion pesos in 2024, up 20% year over year, with a six-year growth rate of 33.8%, according to AMVO. Digital-buyer penetration stands at 84%, well above the 60% global average, and Mexico now ranks 11th in the world. The demand signal is unambiguous. What has not kept pace is the physical infrastructure that fulfills it: warehouses, distribution centers, transport capacity, and above all the last mile. The most reliable investment opportunities often live in exactly this kind of gap, where demand runs ahead of the capacity that serves it.
The key analytical move is to recognize what logistics actually is as an asset. It is infrastructure dressed as a service. Well-located warehouses, distribution networks, and last-mile capacity are assets with structural demand, leases that renew, and real barriers to entry, because prime location and operating scale cannot be improvised. The best logistics real estate behaves less like an operating business and more like inflation-linked infrastructure, with long leases, durable tenants, and cash flows that hold up across cycles. That is why institutional capital has moved so decisively into the category worldwide, and why Mexican industrial real estate has attracted billions in investment as reshoring accelerates.
The value in Mexican logistics compounds through two distinct channels, which is unusual and attractive. The first is the real estate itself, well-located industrial assets that appreciate as demand for space outstrips supply in the corridors that matter. The second is operating consolidation. The sector is fragmented and operates to uneven standards, which means a disciplined investor can build the professionalized operator the market does not yet have, capturing both the asset appreciation and the efficiency gains that scale makes possible. Returns that come from two independent sources are more resilient than returns that depend on a single lever.
The risks deserve a clear accounting. Location risk is paramount: a warehouse in the wrong place is a depreciating liability rather than an appreciating asset, which puts an enormous premium on site selection. The sector is capital-intensive and can be sensitive to interest rates, since real-estate valuations move inversely to yields, so entry discipline and financing structure matter. And logistics demand, while structurally rising, is not immune to a sharp consumer slowdown, so leverage should be calibrated to survive a downturn rather than merely to optimize a boom. None of these undermines the thesis; they define how it must be underwritten.
There is a strategic elegance to the position. You do not need to win the intensely competitive, low-margin business of selling online to profit from e-commerce. You need to own the rails through which everything sold online must physically pass. That is the difference between betting on which retailer wins and owning the infrastructure every retailer depends on, and the latter is the more defensible place to stand.
As consumption in Mexico continues its structural shift online, the constraint moves from demand to fulfillment, and the capital that owns and professionalizes the fulfillment layer captures the difference.
At MountainStone we build and invest in opportunities like this one. If you are developing, operating, or financing logistics in this space, we would welcome the conversation.